
The Maritime Plan Is Authorities, Not Money
The maritime action plan the White House published in February opens with a statistic that does most of the work. Less than one percent of new commercial ships in the world are built in the United States. The plan counts eight active shipbuilding yards, eleven yards
The maritime action plan the White House published in February opens with a statistic that does most of the work. Less than one percent of new commercial ships in the world are built in the United States. The plan counts eight active shipbuilding yards, eleven yards with active build positions and twenty-two repair yards, and sets out to change that.
Read what it actually contains and the shape becomes clear. It proposes fees on foreign-built vessels calling at American ports, modeled at revenue anywhere from tens of billions of dollars over a decade to well over a trillion depending on the rate chosen. It proposes designating maritime prosperity zones, modernizing a loan guarantee program, expanding the merchant marine academy and studying a strategic commercial fleet. What it does not contain is an appropriation, a target number of ships or a mariner workforce number.
From the Battlefield to the Balance Sheet
The sealift fleet is the part of the defense industrial base that nobody counts as defense. Fewer than two hundred American-flag oceangoing vessels of any size serve the international and domestic trades, and the two programs that guarantee military access to commercial capacity are small and full. The maritime security program holds sixty operating agreements, all of them allocated, and the tanker equivalent covers ten product tankers. Every one of those ships also needs a crew that is qualified, available and willing to sail.
That is the constraint a plan of this kind runs into. Shipyard capacity can be built with capital, slowly. Mariners cannot. They require sea time, licensing and years of retention in an industry whose own analysts describe first-year attrition in the range of half the intake at some yards and operators. A fee mechanism that raises money does not by itself produce welders, pipefitters or licensed officers, and that is the gap between the revenue models in the plan and the outcome it describes.
For anyone reading this as an investment question, the honest summary is that the policy direction is settled and the financing is not. Fees require rulemaking and survive litigation or they do not. Loan guarantees require appropriated subsidy. A strategic commercial fleet requires a ship count, a funding line and an operator willing to take the vessels.
The Dual-Use Reality Check
There is no separation here between military and civilian capacity, which is what makes the sector unusual. The same yards, the same suppliers and the same mariners serve commercial cargo and military sealift, and independent analysts put something like seventy to eighty percent of a ship's value in the upstream supplier base rather than in the yard itself. That is where the leverage sits.
It is also where the cost problem sits. Critics of the plan point out that American yards charge a large multiple of global prices, and that the last comparable subsidy era produced a modest number of ships per year even at its best. A fee on foreign tonnage raises the price of shipping into the United States whether or not a single additional ship gets built domestically, and that cost lands on importers and eventually on consumer prices. Any serious read of this policy has to hold both halves: a genuine strategic gap, and a mechanism that functions as a tariff until domestic capacity actually exists.
The Capital Signal
The capital signal is that maritime has moved from neglect to attention without yet moving to money, and the distinction is the whole investment case. Announced authorities are free. Appropriated subsidy, an enacted shipbuilding tax credit or a funded fleet program would be the point at which order books change.
The structural read is to watch the supplier tier and the repair side rather than the yards. Repair and sustainment demand is real today, does not wait on new construction and has a shorter path to revenue. Component makers, propulsion, deck machinery and electrical systems capture most of a ship's value and are less exposed to which yard wins. And watch the workforce numbers at the existing yards, because a yard that cannot hold its people cannot absorb an order book no matter how large it gets. Announcements are abundant in this sector. Delivered hulls are the only thing that has ever settled the argument.
Signal: The maritime plan is a set of authorities and fee models, and none of them build a ship until something in it is actually funded.
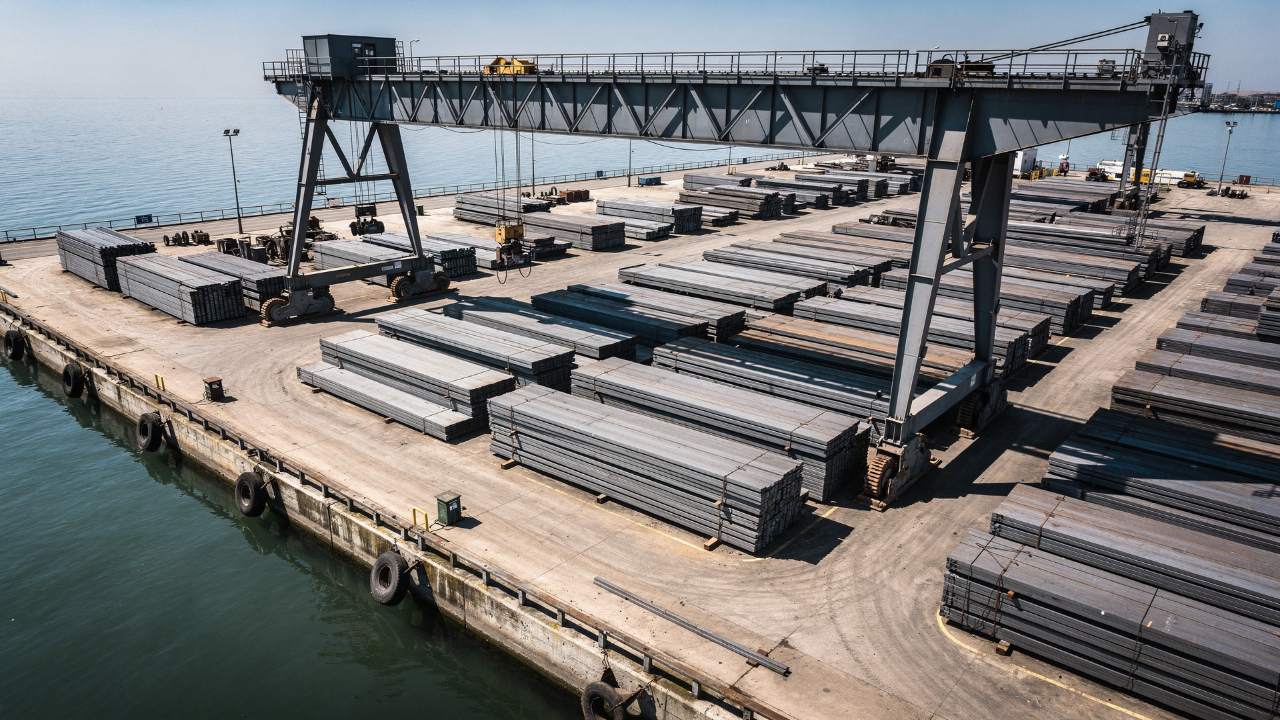
Marcus Cole, Top Margin
Someone Else Is Funding Your Copper Mine
In the third week of October a Canadian miner and a Japanese trading house took a final investment decision on a copper
The Battery Found a Better Customer Than the Car
In the third week of October a solid state battery developer announced plans for a hundred megawatt hour cell production line, targeting

The Startup Moved Into the Prime's Factory
In the middle of October a major missile maker announced a three hundred million dollar expansion of its Texas plant, part of
The Chipmaker Became the Refiner's Banker
In the third week of October one of the three large memory manufacturers said it would put strategic funding into a materials
Join The Strategic Reserve
Get encrypted weekly intelligence. No noise, just mission-critical data