
Defense Venture Capital Has a Duration Problem
Defense technology startups raised about fourteen and a half billion dollars in the first five months of this year, which is more than the whole of last year and an all-time record for the category. The rounds behind that number are familiar. An autonomy and
Defense technology startups raised about fourteen and a half billion dollars in the first five months of this year, which is more than the whole of last year and an all-time record for the category. The rounds behind that number are familiar. An autonomy and hardware company raised five billion dollars at a sixty-one billion dollar valuation in May, roughly double where it was marked a year earlier. An aviation autonomy firm raised two billion at nearly thirteen billion. A maritime autonomy company raised one and three quarter billion at just over nine billion.
Now look at the other side of the ledger. The largest defense technology acquisition anyone has closed recently is a services and space systems deal worth two and six tenths billion dollars, and the sector's most visible public listing this year raised fifteen million on a tiny float. Money is going in at a scale that nothing coming out currently matches.
From the Battlefield to the Balance Sheet
This is a duration problem rather than a valuation argument. Venture capital is priced on the assumption that a position can be realized within the life of a fund, usually through a sale to a larger company or a public listing. Defense revenue does not arrive on that schedule. It arrives on the schedule of appropriations, program milestones and production decisions, and each of those can move by a year for reasons that have nothing to do with the company.
The buyer side is thinner than in most technology sectors as well. The natural acquirers are a handful of primes whose own balance sheets are committed to production expansion, plus private equity, plus a small set of well-funded peers. Antitrust review of consolidation in this industry is real. So the exit that makes a sixty billion dollar private mark liquid has to be a public listing of considerable size, and that requires several consecutive years of revenue the market believes will repeat.
None of this makes the underlying businesses bad. It means the reported record is a measure of capital committed, not of capital returned, and those two numbers can diverge for a long time.
The Dual-Use Reality Check
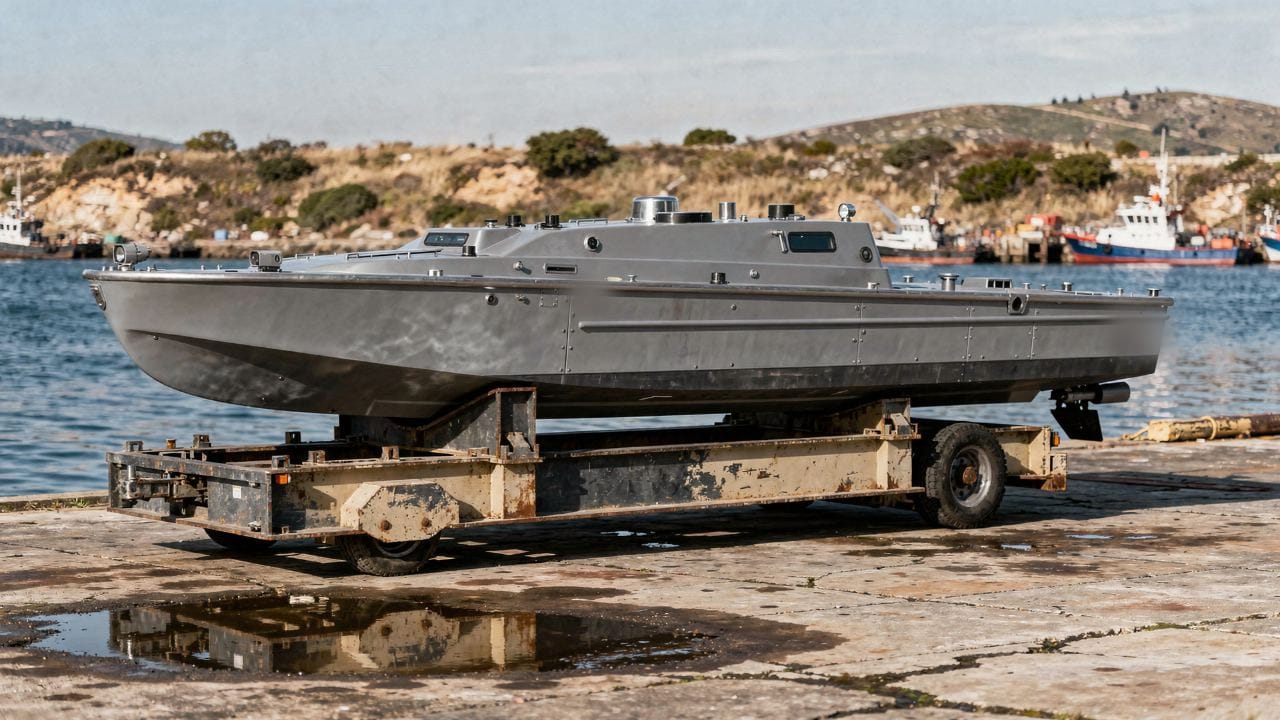
The companies attracting this money are mostly not building weapons in the traditional sense. They are building autonomy stacks, sensor fusion, simulation, manufacturing software and unmanned platforms, and every one of those has a civilian application that is larger by unit volume. Maritime autonomy is also survey work, offshore energy service and port operations. Aviation autonomy is inspection, cargo and agriculture. The simulation and modeling tools being acquired by defense firms this year came out of commercial graphics work.
That dual revenue base is what makes the valuations arguable at all, and it is also the practical test to apply. A defense technology company with a commercial line has a second clock, one that runs on ordinary sales cycles rather than appropriations. A company whose entire path to scale runs through a single government program does not, whatever the comparable multiples say.
The Capital Signal
The capital signal is that the migration of capital toward venture defense is now in its second phase. The first phase was proving that new entrants could win real contracts, and that is settled. The second phase is proving that the returns can be realized, and there is very little evidence on that question yet.
The structural read is to watch for the first large defense technology public listing and what the market pays for it, because that single event will reprice the whole private book. Watch also for the first significant down round or structured financing in the category, which is usually where fixed-return preferred stock and similar instruments start appearing in the capital structure. One such round has already been reported this year alongside a headline valuation. Those structures are not a scandal, they are a sign that late-stage money wants protection it did not previously ask for. For anyone allocating to the industrial side of this story, the more durable position remains the suppliers these companies buy from, who get paid when the factories are built regardless of which brand eventually wins.
Signal: Defense technology has proved it can raise money and has not yet proved it can return it, and the gap between those two is measured in years.
Marcus Cole, Top Margin
Someone Else Is Funding Your Copper Mine
In the third week of October a Canadian miner and a Japanese trading house took a final investment decision on a copper
The Battery Found a Better Customer Than the Car
In the third week of October a solid state battery developer announced plans for a hundred megawatt hour cell production line, targeting

The Startup Moved Into the Prime's Factory
In the middle of October a major missile maker announced a three hundred million dollar expansion of its Texas plant, part of
The Chipmaker Became the Refiner's Banker
In the third week of October one of the three large memory manufacturers said it would put strategic funding into a materials
Join The Strategic Reserve
Get encrypted weekly intelligence. No noise, just mission-critical data