
Arms Exports Grew, but Not the Part You Think
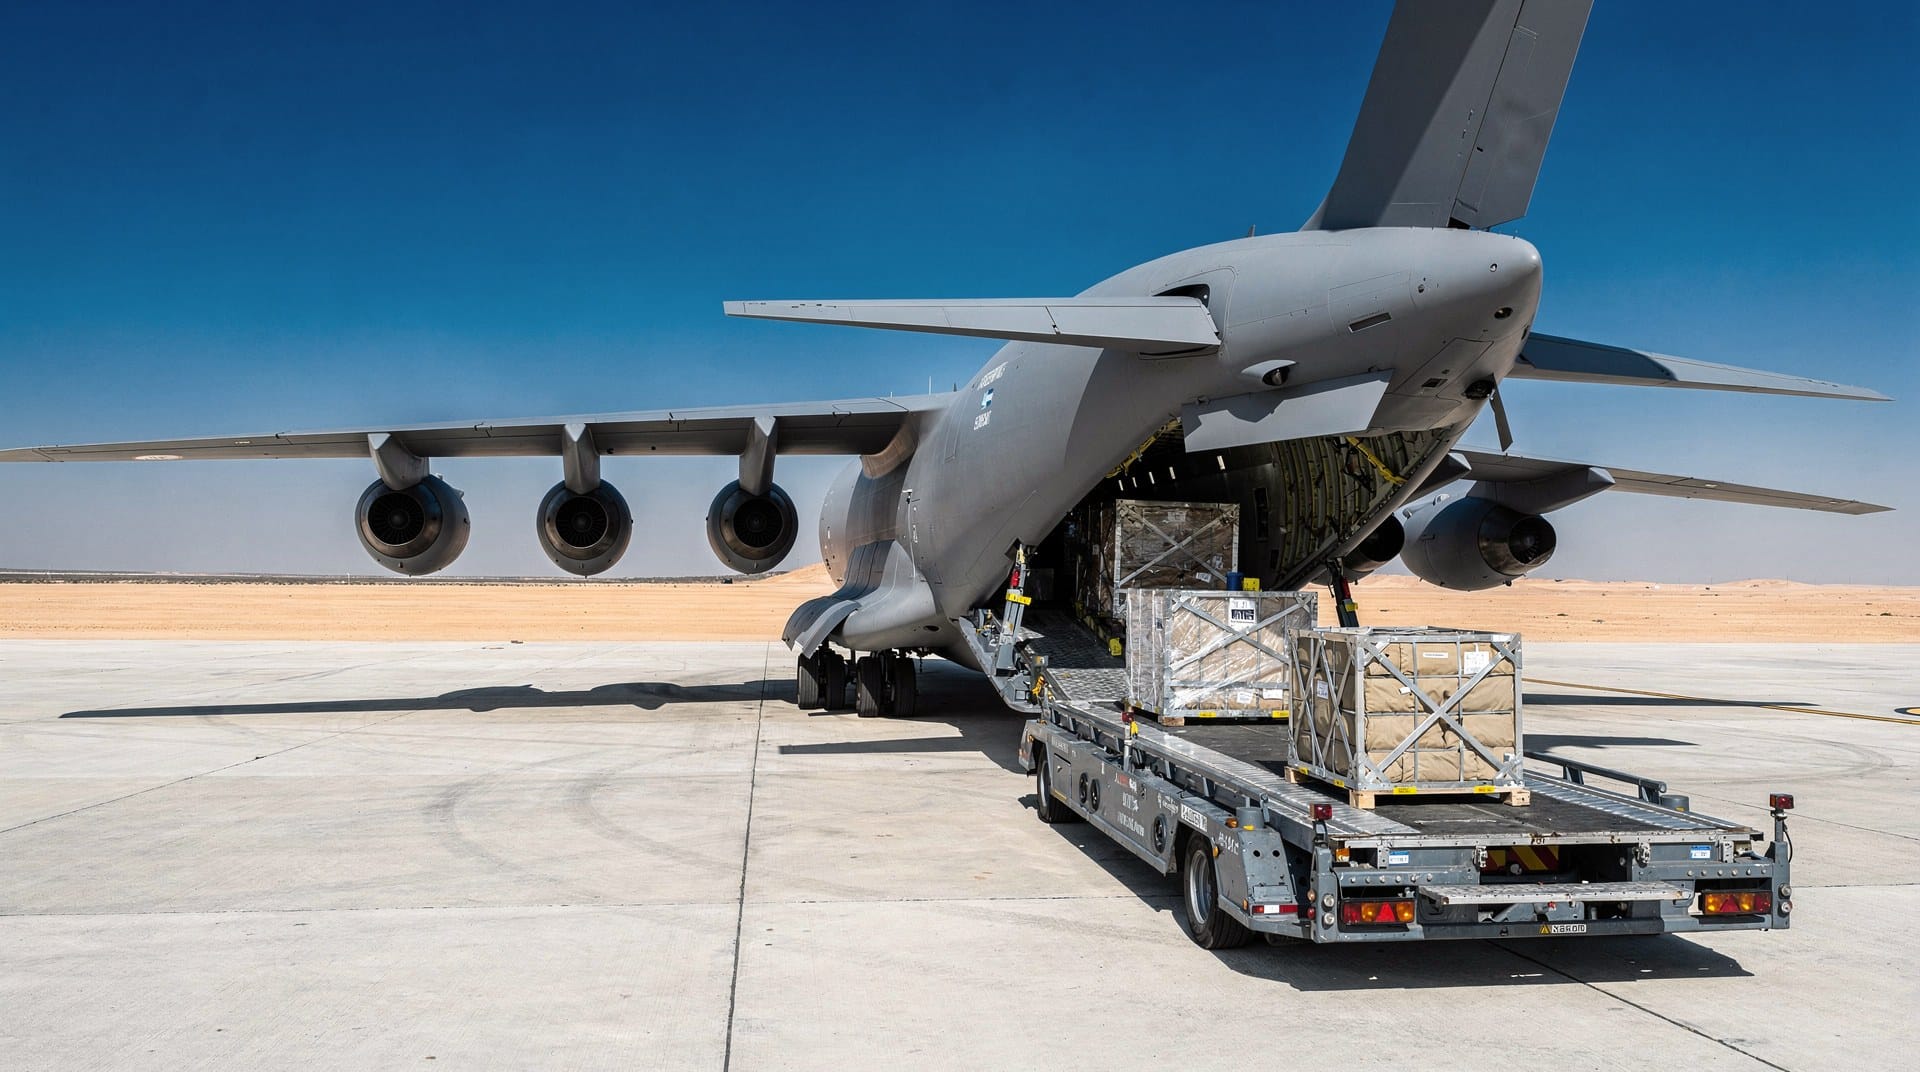
American international defense sales reached $331.2 billion in fiscal 2025, up from $318.7 billion the year before. That is roughly four percent growth and another record, and it is the number that made the headlines. The composition underneath it is the part worth reading.
American international defense sales reached $331.2 billion in fiscal 2025, up from $318.7 billion the year before. That is roughly four percent growth and another record, and it is the number that made the headlines. The composition underneath it is the part worth reading.
Direct commercial sales, where a company sells to a foreign government under an export licence without the United States government acting as intermediary, came in at $226.8 billion against $200.8 billion a year earlier, a rise of nearly thirteen percent. Foreign military sales, the government-to-government channel that most people mean when they say arms exports, declined. The topline grew because the commercial channel more than covered a shrinking official one.
From the Battlefield to the Balance Sheet
These two channels are different businesses with different economics. In a foreign military sale the United States government contracts with the supplier and manages the case, which brings standardization, financing arrangements and a great deal of process. Direct commercial sales put the manufacturer in front of the customer, and the negotiation, pricing, delivery schedule and support arrangements are the company's own.
A shift toward the commercial channel therefore means margin and control moving to the manufacturer, along with the risk. It usually also means faster contracting, which matters enormously to buyers who have watched official cases take years to move. When the government channel is congested, demand does not disappear, it reroutes, and that is the most plausible reading of a thirteen percent jump on one side against a decline on the other.
For allocators the consequence is that export exposure is no longer well captured by tracking congressional notifications and official case values. A growing share of the business does not appear there in the same way, which makes company disclosure and licence activity the better guide.
The Dual-Use Reality Check
Export demand at this scale is an industrial policy instrument whether or not anyone calls it one. Foreign orders fill American production lines, and they do it with money that is not appropriated, which means they smooth the domestic budget cycle and justify capacity that domestic demand alone would not support. A munitions line running for two customers has better unit economics than one running for a single customer, and the second customer is increasingly foreign.
That flows straight into the supplier base most of this newsletter has been tracking. Castings, forgings, energetics, optics and electronic components see the combined demand, not the domestic slice, and the capacity investments being financed today are underwritten partly by export volume. It also means American manufacturing employment in these categories is more exposed to allied budget decisions than to the domestic topline, which is an unusual position for a sector that most people assume is purely a function of Washington.
The obvious risk is the mirror image. Export demand that arrived quickly can leave quickly, and capacity built against it carries that exposure. Allied procurement runs on political cycles that no American manufacturer controls, and a line sized for two customers is an expensive line when one of them stops ordering.
The Capital Signal
The capital signal is that the growth in this business is coming through the channel with less government mediation, and that changes who captures the value. In the commercial channel the manufacturer keeps more of the economics and owns the customer relationship, including sustainment, which is the long-tail revenue that matters more than the initial sale.
The structural read is to watch delivery rather than order intake. Record sales figures describe agreements, and the constraint on converting them into revenue is the same production capacity constraint that limits domestic programs, which means a growing order book against a fixed line is a backlog rather than a business. The companies worth attention are the ones expanding capacity against export demand and disclosing what portion of that demand is committed rather than notified. A record year in signed value and a flat year in delivered units are the same year described two different ways.
Signal: The export record was made in the commercial channel, which puts more margin and more risk in the manufacturer's hands than the official numbers suggest.
Marcus Cole, Top Margin
Someone Else Is Funding Your Copper Mine
In the third week of October a Canadian miner and a Japanese trading house took a final investment decision on a copper
The Battery Found a Better Customer Than the Car
In the third week of October a solid state battery developer announced plans for a hundred megawatt hour cell production line, targeting

The Startup Moved Into the Prime's Factory
In the middle of October a major missile maker announced a three hundred million dollar expansion of its Texas plant, part of
The Chipmaker Became the Refiner's Banker
In the third week of October one of the three large memory manufacturers said it would put strategic funding into a materials
Join The Strategic Reserve
Get encrypted weekly intelligence. No noise, just mission-critical data