
A Market Created by Statute
Until the first of July this year, no American state, local or tribal agency had legal authority to bring down a drone. Four federal departments did, and nobody else. A provision in last December's defense authorisation changed that, and the interim rule implementing it
Until the first of July this year, no American state, local or tribal agency had legal authority to bring down a drone. Four federal departments did, and nobody else. A provision in last December's defense authorisation changed that, and the interim rule implementing it took effect at the start of July with a two tier structure. Detection and tracking are open to any qualifying agency through an online certification. Mitigation, meaning actually stopping the aircraft, requires in-person training at a federal facility and separate spectrum authorisation for anything that emits.
A month after the rule took effect, the Homeland Security research arm awarded a five year counter-drone contract vehicle with a one and a half billion dollar ceiling to twelve named companies. The authority itself expires at the end of 2031.
From the Battlefield to the Balance Sheet
This is a market that exists because a statute says it does, and the shape of the statute is the shape of the market. The two tier design splits it cleanly. Detection is a low barrier business, sold to a very large number of buyers, competing on price and integration with existing security systems. Mitigation is a small number of buyers, gated by federal training and spectrum licensing, and the barrier to entry is regulatory rather than technical.
Those two businesses have entirely different economics and they are routinely lumped together in the same market forecast. Sensing hardware becomes a commodity quickly, because passive radio frequency detection and small radars are not hard to build and the customer list is every airport, stadium, prison and utility in the country. Effectors do not, because the customer must be trained and licensed to use them, which protects the incumbents on the approved vendor list far more effectively than any patent.
The sunset date is the other term that deserves attention. A five year authority with a fixed expiry gives a defined procurement window and creates an obvious cliff. Companies building to this demand are building against a clock that requires Congress to act again, and any capacity sized for a permanent market is sized wrong unless that happens.
The Dual-Use Reality Check
The technology came from the military side and the volume is now civil, which is the pattern this newsletter keeps finding. Radio frequency sensing, small radar, optical tracking and the software that fuses them were developed for base defense. The buyers are now police departments, airport authorities, stadium operators and critical infrastructure owners.
The demand signal, though, has come mostly from outside the United States. A run of European airport closures through late last year, several of them lasting hours and affecting tens of thousands of passengers, did more to establish what an incident costs than any domestic event has. That is the number this market actually runs on. An airport that loses three hours of operations can calculate what a detection system is worth to it, and that calculation, not a federal grant, is what turns a pilot into a fleet purchase.
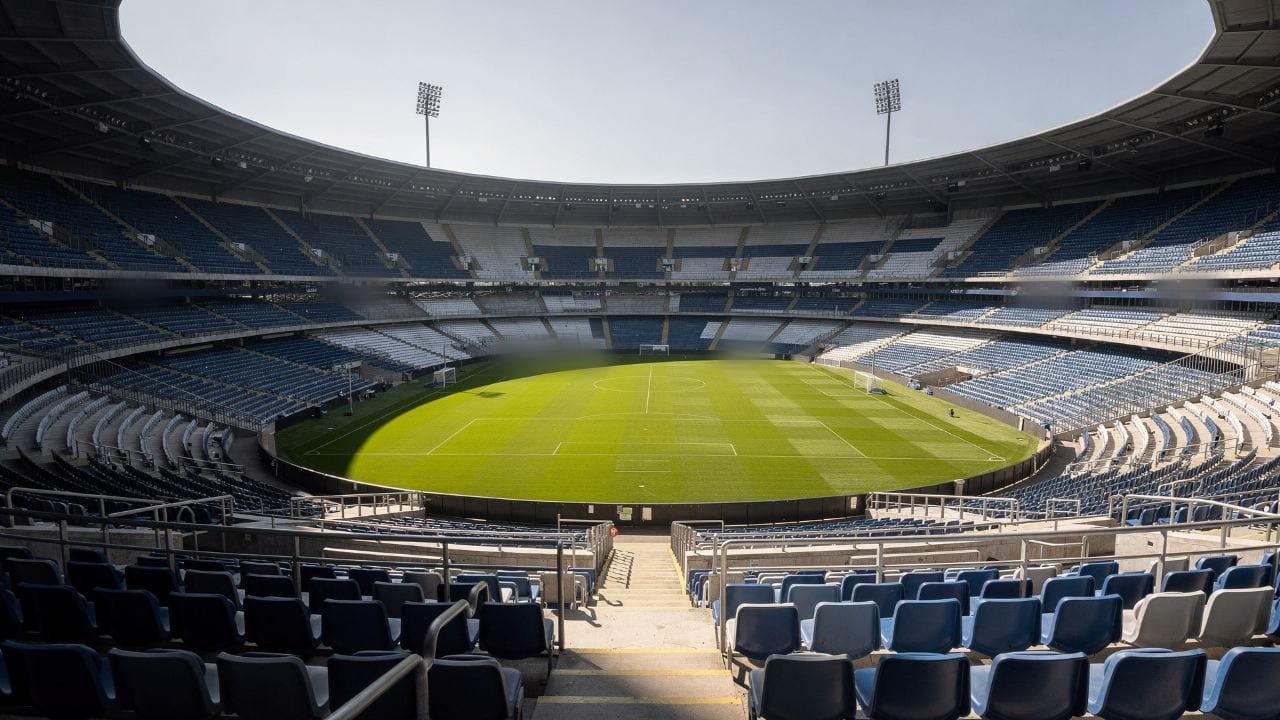
Domestically the forcing event is a scheduled one. Aviation authorities established restricted airspace around stadiums and fan sites for next year's football tournament, with penalties attached, which creates a hard deadline for a defined set of venues. Deadlines of that kind reliably produce procurement, and they equally reliably produce equipment that sits unused afterwards.
The Capital Signal
The capital signal is that regulatory authority, not capability, is the scarce asset in this sector, and it has just been partially released on a timer. The companies on the approved vehicle have a five year head start on a customer base that could not legally buy from anyone before this summer.
The structural read is to separate the tiers when valuing anything here. Detection revenue is real, recurring and will compress in price as the field fills. Mitigation revenue is smaller, stickier and effectively licensed. A company selling both will report them together and describe the blended growth rate, and the blended rate will flatter the part that is commoditising. Watch also for how many agencies actually complete the mitigation training, because that number, published or not, is the true size of the effector market. Authority granted is not the same as authority used, and a statute can create a market considerably faster than institutions can staff one.
Signal: Counter-drone became a civil market on a datable day by act of Congress, and the tier that is protected by licensing is the only part of it that will hold its margin.
Marcus Cole, Top Margin
Someone Else Is Funding Your Copper Mine
In the third week of October a Canadian miner and a Japanese trading house took a final investment decision on a copper
The Battery Found a Better Customer Than the Car
In the third week of October a solid state battery developer announced plans for a hundred megawatt hour cell production line, targeting

The Startup Moved Into the Prime's Factory
In the middle of October a major missile maker announced a three hundred million dollar expansion of its Texas plant, part of
The Chipmaker Became the Refiner's Banker
In the third week of October one of the three large memory manufacturers said it would put strategic funding into a materials
Join The Strategic Reserve
Get encrypted weekly intelligence. No noise, just mission-critical data